You locked your mortgage rate, and then rates dropped. It is one of the most frustrating spots in homebuying, because the lock that protected you from a spike is now the thing keeping you from a better payment. The 10-year Treasury yield, which mortgage rates follow closely, closed last week near 5.10 percent after touching about 5.3 percent on Wednesday. If you locked before that move, you may be wondering whether anything can be done.
Two weeks ago, the Fed hiked rates for the first time in three years, and the market quickly priced in a real chance of a second hike in October, with odds running as high as 70% or more at one point last week. By today, those odds had collapsed to somewhere around 17% to 25%. That's a genuinely large swing, and it happened for two separate reasons, not one.
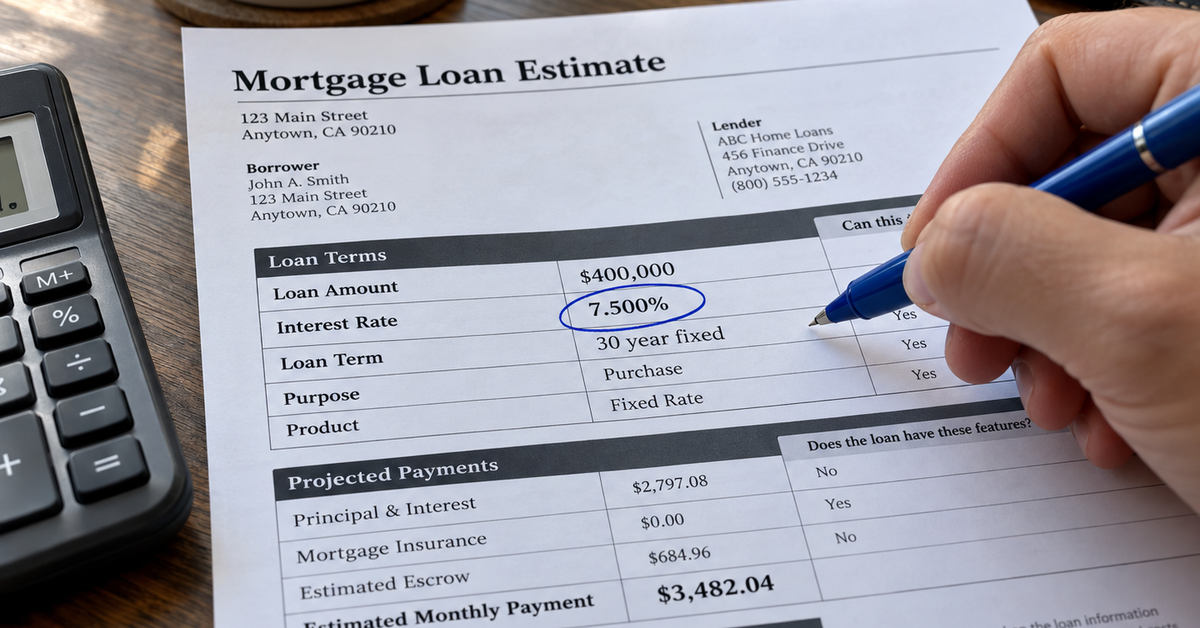
Two things are true about the housing market right now, and they're pulling in opposite directions. Mortgage rates just hit their highest level in a year, some trackers put the 30-year near 7.5%, driven by an oil price spike tied to the conflict in the Middle East and inflation that won't cool off. At the same time, buyers are backing away in response, and that's opening up real leverage for anyone who's still able to buy.
The Fed just did something it hasn't done in three years: it raised rates. On September 16, the Federal Open Market Committee voted unanimously, 12-0, to raise the federal funds rate a quarter point, to a target range of 3.75% to 4.00%. It's the first hike since 2023, and the committee's own projections point to at least one more before the end of the year.
If you've got a listing that's been sitting longer than it should, you're not imagining it. Mortgage rates just touched their highest levels in about a year, national averages running close to 7%, and the 10-year Treasury yield climbed to its highest point since late 2023. That's pricing some of your buyer pool out of homes they could have afforded just a few months ago, and it's showing up in days-on-market numbers across a lot of markets right now.
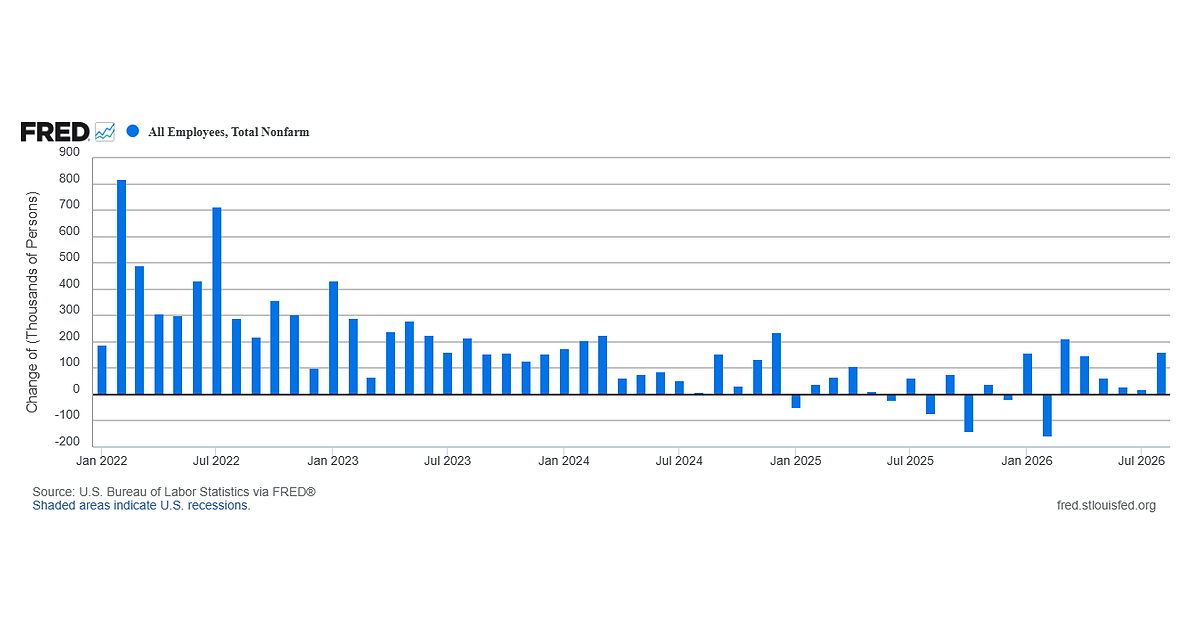
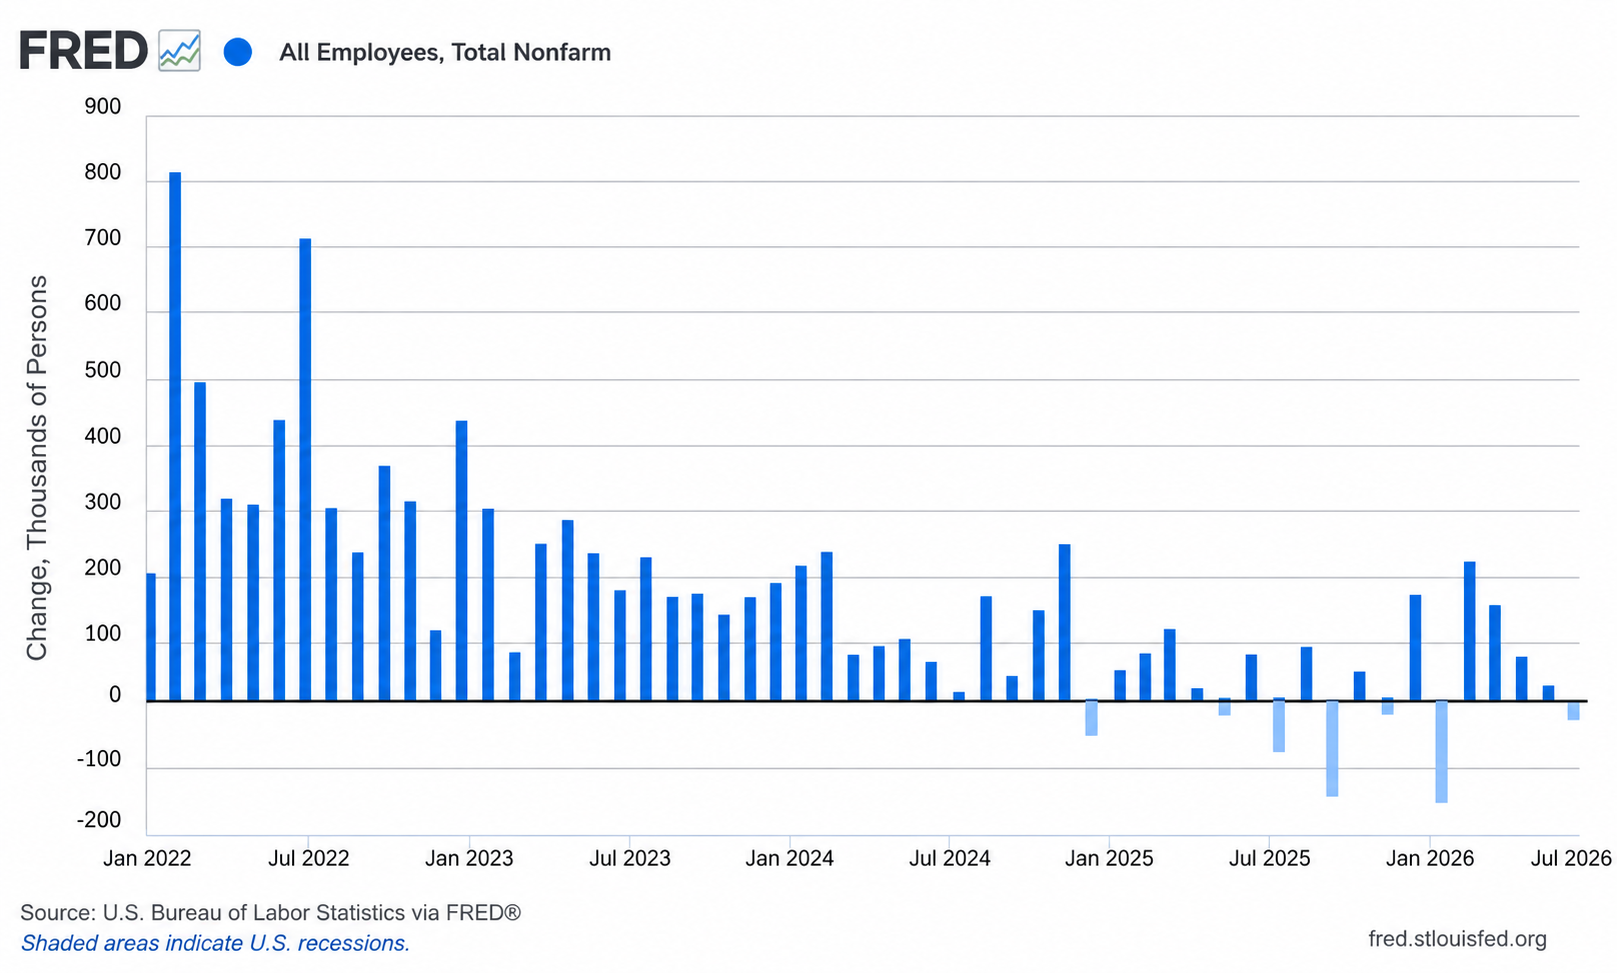
After a weak summer for hiring, the job market just came roaring back — and for anyone watching mortgage rates, the reaction might not be the one you'd expect. Here's why strong economic news can actually push rates the wrong way for buyers. The Headline: A Big Beat The August jobs report showed the U.S. economy added 162,000 jobs — nearly triple the roughly 55,000 economists had forecast. Unemployment held steady at 4.1%, and wages rose 0.3% on the month. One caveat: these monthly numbers are volatile and get revised. The steadier read is the three-month average, running around 71,000 jobs a month — not a booming economy, but a solid, resilient one. And "solid and resilient" is exactly what changes the Fed's calculus. On its face, that's good news for the economy — more people working, hiring bouncing back, the labor market looking healthier than the summer's gloom suggested. But "good for the economy" and "good for mortgage rates" are often two very different things, and this is one of those times. Why a Strong Jobs Report Can Push Rates Up Here's the counterintuitive part that trips people up. Mortgage rates don't track the health of the job market directly — they track the bond market and, above all, expectations about what the Federal Reserve will do. And a strong jobs report shifts those expectations in a direction that tends to lift rates. The logic: when the economy looks weak, investors expect the Fed to cut rates, and mortgage rates ease in anticipation. When it looks strong — like it just did — that flips. A solid labor market gives the Fed less reason to cut and more room to stay tight, or even hike to keep inflation in check. Bond yields rise on that expectation, and mortgage rates follow. And that's exactly what played out. Right after the report, the 10-year Treasury yield — the benchmark mortgage rates track most closely — pushed higher, toward its highest levels in well over a year. At the same time, the market's estimate of the odds that the Fed raises rates at its September meeting climbed to roughly two-thirds, up sharply from around a third just a couple of weeks earlier. A solid labor market took a rate cut off the table and put a hike squarely on it. So the same report that's reassuring for job seekers can be a headwind for buyers watching rates. It's one of the genuine oddities of this market: sometimes softer economic news is what buyers are quietly rooting for. Not sure what today's market means for your plans? Rates move on news like this, and nobody can promise where they head next. But I can help you understand your real options right now — including a free float-down if rates drop after you lock. Let's run your numbers. Book a free 15-minute call → The Timing Makes This One Matter More This report carries extra weight because of when it landed. It's the last jobs report the Federal Reserve will see before its meeting in mid-September, where it decides its next move on interest rates. Some Fed officials have already been openly arguing for a rate hike to fight stubborn inflation. A strong labor market hands those hawks more ammunition — it's harder to justify cutting rates when the economy is adding jobs at nearly triple the expected pace. Mortgage rates were already sitting near their highest level in over a year heading into this report. A strong number doesn't help that picture — it removes one of the arguments for rates falling, right before a pivotal decision. But the jobs report isn't the last word. Fed officials have signaled they want to see the upcoming inflation data — the CPI reading due in the days before the meeting — before deciding between a hike and a hold. That inflation print is really the deciding input now. And lurking behind it is oil: energy prices have been climbing on tensions in the Middle East, and higher oil feeds directly into inflation, which pushes yields and rates up. The flip side is the one piece of good news for rate-watchers — if those geopolitical tensions ease and oil prices come back down, it would take pressure off inflation and, potentially, off rates. That's the wild card worth watching between now and the Fed meeting. What This Means If You're Buying or Refinancing Let me give you the honest read, because this is where buyers can talk themselves into a costly wait. Don't count on rates dropping soon. The stronger the economy looks, the less pressure there is on the Fed to ease, and the harder it is for rates to fall meaningfully. If your plan has been to sit on the sidelines until rates come down, this report is a reminder that the timing of that is genuinely uncertain — and you'd be paying rising home prices while you wait. Trying to time the exact bottom rarely works. Even the Fed doesn't know where rates go next. Buyers who wait for the "perfect" rate often miss the right house, and the house matters more than a fraction of a point on the rate — you marry the home and date the rate. If the numbers work today and you find the right place, that's usually a better position than holding out for a forecast nobody can promise. There are ways to manage the rate. Temporary buydowns, seller concessions to cover points, and adjustable options all exist precisely for markets like this. And a free rate float-down means if you lock now and rates fall before closing, you can still capture the lower rate — which takes some of the "what if I lock at the wrong time" worry off the table. The Bottom Line August's jobs report was a genuine rebound — the labor market looks a lot healthier than it did a month ago. But for buyers, strong economic news is a double-edged sword: it eases fears of a weakening economy while removing some of the pressure that could have pushed mortgage rates down, especially with a Fed decision looming. The smart move isn't to chase a rate forecast. It's to know your real numbers, understand your options, and be ready to act when the right home and a workable rate line up. If you want help figuring out what today's market means for your specific situation, that's exactly what I'm here for. Want to know what today's rates mean for your budget? Let's run your real numbers — what you'd qualify for, your payment, and how to protect yourself if rates keep moving. Free, no pressure. Book a free call → | Get a free rate quote → Nate Moghadam is a mortgage loan officer at Fairway Independent Mortgage Corporation, licensed in Massachusetts and 13 other states. NMLS #906770 | Company NMLS #2289. This content is for informational purposes only and does not constitute financial advice or a commitment to lend. Interest rates and market conditions are subject to change without notice. Rate and economic figures cited reflect data available on the date of writing and are not a quote or offer of credit; your rate depends on your individual circumstances. All loans subject to credit and property approval. Equal Housing Opportunity. Legal Disclosures.
This morning brought a genuine surprise — and for anyone watching mortgage rates, it moved things in the direction buyers have been hoping for. Here's what happened with July's jobs report, in plain English, and what it actually means for your rate. The Headline: The Economy Lost Jobs The July jobs report showed the U.S. economy lost 23,000 jobs last month. That's not a small miss — forecasters had expected a gain of around 83,000. Instead of adding jobs, the economy shed them, which is the kind of number that gets the market's attention fast. There was a second data point that looked good on the surface but wasn't: the unemployment rate actually ticked down to 4.1%. Normally that's positive news. This time it wasn't, because unemployment fell for the wrong reason — people left the workforce rather than found jobs. Labor force participation dropped to 61.4%, its lowest level in more than five years. When people stop looking for work, they're no longer counted as unemployed, which can make the headline rate look better even as the underlying picture weakens. Why Mortgage Rates Eased Here's the part that matters for your wallet. When the economy shows weakness, investors tend to move money into the safety of bonds. That pushes bond prices up and bond yields down — and mortgage rates track the 10-year Treasury yield closely. That's exactly what happened. After the report, the 10-year Treasury yield fell to around 4.62%, and shorter-term yields dropped even more sharply. Mortgage rates followed. Just earlier this week, the average 30-year fixed had been climbing toward 7%. After the jobs news, it eased back into the mid-6% range. So unlike the last few weeks — when a hawkish Fed was pushing rates up — this report nudged them back down. It's a meaningful shift in tone, even if it's only one report. Wondering if this is your window? Rates move daily, and nobody can promise where they go next — but I can help you understand your real options right now, including a free float-down if rates drop after you lock. Let's run your numbers. Book a free 15-minute call → What It Means for the Fed This report lands the Federal Reserve in a genuinely difficult spot. Just a couple of weeks ago, at their last meeting, several Fed members were actually pushing to raise rates to fight stubborn inflation — the most hawkish tone in years. Now, a jobs contraction complicates that entirely. After the report, traders quickly cut the odds of a rate hike at the Fed's September meeting to around 44%. In other words, the market rapidly repriced from "the Fed might hike" toward "the Fed probably holds, and might eventually need to cut." But — and this is the honest part — the Fed is boxed in. Inflation is still elevated and sticky, sitting above their 2% target. A weakening job market argues for lower rates. Stubborn inflation argues against it. The Fed can't fully satisfy both at once, which is why policymakers are openly divided. There's no clean signal here, and one month of data doesn't settle it. What This Means If You're Buying or Refinancing Let me give you the straight version, without the hype you'll see elsewhere. This is a real easing, but not a green light to "wait for more." Rates came off their recent highs, which is genuinely good news if you've been watching them creep toward 7%. But one soft jobs report doesn't guarantee a trend, and the sticky-inflation problem hasn't gone away. Anyone telling you rates are definitely about to tumble is guessing — the Fed itself won't make that call. Trying to time the exact bottom is how people miss good windows entirely. If softer rates were your holdup, this is worth a real look. For a buyer who was on the fence specifically because of rates, this easing is exactly the kind of moment worth running your actual numbers — what you'd qualify for, what the payment looks like now versus a few weeks ago, whether it changes your comfortable price range. You can lock and still benefit if rates fall further. This is where a free float-down matters: if you lock in now and rates drop before you close, you can capture the lower rate. That takes some of the "what if I lock at the wrong time" anxiety off the table, which is especially useful in a choppy, headline-driven market like this one. The house still matters more than the rate. The reframe I always come back to: you marry the house and date the rate. If the right home comes along and the numbers work, a slightly-better-or-worse rate shouldn't be the thing that decides it — you can refinance later if rates keep falling. Rates will keep moving; the right house won't wait. The Bottom Line July's job losses surprised the market, pushed bond yields down, and eased mortgage rates off their recent highs — a welcome shift after weeks of upward pressure. But with inflation still sticky and the Fed divided, this is a loosening of pressure, not a clear path to sharply lower rates. For buyers, the smart move isn't to chase a forecast. It's to know your real numbers, understand your options, and be ready to move when the right home and a workable rate line up. If you'd like help figuring out what today's market means for your specific plans, that's exactly what I'm here for. Want to know what today's rates mean for your budget? Let's run your real numbers — what you'd qualify for, your payment, and how to protect yourself if rates keep moving. Free, no pressure. Book a free call → | Get a free rate quote → Nate Moghadam is a mortgage loan officer at Fairway Independent Mortgage Corporation, licensed in Massachusetts and 13 other states. NMLS #906770 | Company NMLS #2289. This content is for informational purposes only and does not constitute financial advice or a commitment to lend. Interest rates and market conditions are subject to change without notice. Rate figures cited reflect approximate national averages on the date of writing and are not a quote or offer of credit; your rate depends on your individual circumstances. All loans subject to credit and property approval. Equal Housing Opportunity. Legal Disclosures.
The Federal Reserve met this week, and if you're waiting for mortgage rates to fall before you buy or refinance, the news wasn't what you were hoping for. Here's what happened, in plain English, and what it actually means for your rate. What the Fed Did The Fed left its benchmark rate unchanged at a range of 3.5% to 3.75% — the move most people expected. But the headline isn't the hold. It's the split: three members of the committee voted to raise rates, the most dissents in favor of a hike since 2016. That direction matters. For most of the past year, the debate was about when the Fed would cut. This meeting flipped that script — the pressure inside the room right now is toward hiking, not cutting, because inflation is still running above the Fed's 2% target and a few officials want to act on it. Fed Chairman Kevin Warsh said the committee "will not hesitate to act" to bring inflation down, and pointedly declined to give any forward guidance about where rates go next. Why Mortgage Rates Actually Went Up Here's the part that trips people up every time: the Fed holding its rate steady did not keep mortgage rates steady. In fact, mortgage rates rose after the meeting. That's because mortgage rates don't track the Fed's benchmark rate directly. They track the bond market — specifically the 10-year Treasury yield. And after the Fed's hawkish tone and those three dissents, bond yields jumped: the 10-year climbed toward 4.7%, and the 30-year Treasury topped 5.2%, its highest level since 2007. When Treasury yields rise, mortgage rates follow. The average 30-year fixed is now hovering in the high-6% range, near a one-year high. So the takeaway isn't "the Fed held, so my rate is safe." It's the opposite: the market read the Fed as more willing to fight inflation, and rates ticked up in response. Trying to time your rate? I can't predict the market — nobody can — but I can help you understand your real options right now, including a free float-down if rates drop after you lock. Let's talk through your numbers. Book a free 15-minute call → The Inflation Report: Good News With an Asterisk The day after the Fed meeting, we got the June reading of the PCE index — the Fed's preferred inflation gauge. And on the surface, it was encouraging: headline inflation cooled to 3.7% year over year (down from 4.1%), and core inflation eased to 3.3%. But here's the asterisk, and it's a big one. That cooldown was driven almost entirely by falling gas prices — energy goods dropped 9.2% in June, the biggest monthly decline since 2022, during a brief ceasefire in the Middle East conflict. That ceasefire has since broken. Gas is back above $4 a gallon, and oil has climbed sharply in the second half of the month. In other words, the one genuinely good inflation number we got is already stale. Nearly every analyst reading it said the same thing: the June cooldown is likely a temporary blip, and inflation may well tick back up in the July and August reports as energy prices reverse. The Fed knows this too — which is exactly why three members are pushing to hike. What This Means If You're Buying or Refinancing Let me be straight with you, because this is where a lot of buyers make a costly mistake. Waiting for rates to drop is a weak bet right now. The Fed's next move might be a hike, not a cut. The one good inflation number is already undone by rising oil. And the market is pricing in more inflation risk, not less. Nobody can promise where rates go, but the current momentum is not in the "rates are about to fall" direction. If your plan is to sit on the sidelines until rates come down, you may be waiting a long time — and paying rising home prices while you wait. The house matters more than the rate. Here's the reframe I give clients: you marry the house, you date the rate. If you find the right home and the numbers work at today's rate, waiting for a hypothetical better rate can cost you the house — and you can always refinance later if rates fall. Meanwhile, if rates rise further, buying now looks smart in hindsight. There are ways to manage the rate risk. Rate buydowns, seller concessions to cover points, and adjustable-rate options all exist for a reason. And a free rate float-down means if you lock now and rates drop before closing, you can still capture the lower rate. The right move depends entirely on your situation — which is exactly the kind of thing worth talking through with someone before you decide. The Bottom Line The Fed held rates, but the tone turned hawkish, mortgage rates rose, and the one encouraging inflation number is already being reversed by rising oil prices. For anyone waiting on the sidelines for a big rate drop, the honest read is: don't count on it happening soon. That doesn't mean rush into a bad decision. It means make your decision based on the home, your budget, and the real numbers in front of you — not a rate forecast that even the Fed won't make. If you want help figuring out what today's market means for your specific plans, that's what I'm here for. Wondering what today's rates mean for your budget? Let's run your real numbers — what you'd qualify for, what your payment looks like, and how to protect yourself if rates move. Free, no pressure. Book a free call → | Get a free rate quote → Nate Moghadam is a mortgage loan officer at Fairway Independent Mortgage Corporation, licensed in Massachusetts and 13 other states. NMLS #906770 | Company NMLS #2289. This content is for informational purposes only and does not constitute financial advice or a commitment to lend. Interest rates and market conditions are subject to change without notice. Rate figures cited reflect national averages on the date of writing and are not a quote or offer of credit; your rate depends on your individual circumstances. All loans subject to credit and property approval. Equal Housing Opportunity. Legal Disclosures.
This morning's June jobs report came in significantly weaker than expected — and unlike last month's hot report, this one actually pushed mortgage rates lower. If you're buying a home or watching rates, here's what happened and what it means for you. What the Jobs Report Showed The U.S. economy added just 57,000 jobs in June — well below the roughly 110,000–115,000 economists expected, and the slowest month of hiring since February. On top of the miss, the prior two months were revised down by a combined 74,000 jobs, which makes the labor market look softer than previously believed. This is essentially the opposite of the report we got a month ago, when the economy blew past expectations and rates jumped. One detail worth noting for anyone in the housing world: while construction added jobs overall, residential building construction actually lost positions in June — a small but real soft spot in the part of the economy closest to housing. A weak jobs report is generally good news for mortgage rates. When the labor market cools, it eases inflation pressure and revives the case for the Federal Reserve to cut rates rather than hike them. That takes some of the upward pressure off — which is exactly what we saw in the market's reaction this morning. The Unemployment Rate Dropped — But for the Wrong Reason Here's the part that seems contradictory at first: even though hiring came in weak, the unemployment rate actually fell to 4.2%. How can both be true? The answer is in the labor force participation rate, which dropped 0.3 percentage points to 61.5% — its lowest level in about five years. The unemployment rate didn't fall because more people found jobs — it fell (from 4.3% to 4.2%) because people left the workforce entirely and stopped being counted as unemployed. That's a soft signal underneath a headline that looks strong on the surface. For the Fed and the bond market, this reinforces the "cooling economy" read rather than contradicting it. A shrinking labor force alongside weak hiring is not a sign of strength — and the market treated it accordingly. How Rates Reacted Mortgage rates track the 10-year Treasury yield, which moves on the bond market's read of inflation and growth. On weak economic data, the 10-year typically falls — and it did. Following this morning's report, the 10-year Treasury yield slipped to 4.478%, and the national average 30-year fixed mortgage rate eased to around 6.6%. Not a dramatic move, but a move in the right direction for buyers — and a welcome change from the upward pressure of the past several weeks. Wondering what today's move means for your purchase? I follow the market in real time and can give you an honest read on where rates are and what your options look like. Book a free call. Book a free 15-minute call → Is This the Start of a Trend? One report doesn't make a trend — and that's worth saying plainly. A single weak jobs number, especially one distorted by falling labor force participation, isn't enough on its own to conclude that rates are headed steadily lower. It's one data point in a noisy series that gets revised, sometimes significantly, in the months that follow. It's also worth remembering the bigger backdrop. Just a couple weeks ago, the Federal Reserve signaled at its June meeting that its next move could be a hike, with markets pricing in a possible increase as soon as October. Today's weak jobs data pushes against that narrative — and with new Fed Chair Kevin Warsh, who was appointed with a mandate favoring lower rates, some economists think a soft jobs report could give him cover to pivot toward a cut sooner than the June dot plot implied. But there's a genuine catch keeping the Fed boxed in: inflation is still too high. Average hourly earnings rose 3.5% in June, still running below the most recent 4.2% inflation reading, and the Fed can't cut aggressively while inflation sits well above its 2% target. So even a rate-cut-inclined Fed chair faces real constraints. Geopolitical developments remain a wildcard on top of all this, capable of moving oil prices and inflation expectations in either direction on short notice. The honest read: today is a positive data point for rates, but the broader picture is still a tug-of-war. For the full context on the Fed's recent shift, see what the June Fed meeting means for mortgages. What Buyers Should Do The practical takeaway hasn't fundamentally changed, even on a good day for rates: If you're under contract and closing soon — this is a favorable moment to lock, since rates ticked down. Lock with a float-down option so you're protected if rates rise but can still capture further improvement if this cooling trend continues. At Fairway, the float-down is available at no additional cost, which removes the usual trade-off between certainty and upside. If you're still shopping — today's move is encouraging, but don't try to perfectly time it. A single report can reverse. Focus on your financial readiness and finding the right home; the rate can be refinanced later if this cooling trend turns into a genuine downtrend. For a full framework, see whether to lock your rate now or wait. The Bottom Line June's jobs report was weak — just 57,000 jobs against expectations near 115,000 — and the details underneath were soft too, with the drop in unemployment driven by people leaving the workforce rather than finding jobs. Bond yields fell in response, and mortgage rates eased to around 6.6%. For buyers, this is a positive data point after a stretch of upward pressure. But it's one report, not a trend, and the broader environment — a Fed leaning hawkish, geopolitical uncertainty — still cuts both ways. Watch cautiously, lock when it makes sense for your timeline, and don't let the noise pull you out of the market when the right home is in front of you. Want a straight read on what to do with your rate right now? I work with buyers across Massachusetts and 13 other states and watch the market every day. Book a free call and I'll give you an honest answer based on your situation. Book a free call → | Start my pre-approval → Nate Moghadam is a mortgage loan officer at Fairway Independent Mortgage Corporation, licensed in Massachusetts and 13 other states. NMLS #906770 | Company NMLS #2289. This content is intended for informational purposes only and does not constitute financial or investment advice. Mortgage rates change daily and vary based on individual borrower profiles and market conditions. This is not a commitment to lend. Contact a licensed loan officer to discuss your specific situation. Equal Housing Lender. Fairway Independent Mortgage Corporation Disclosures.
It's one of the most stressful moments in the homebuying process: you got pre-approved a few weeks ago, you were comfortable with where rates were — and then the market moved. Now rates are higher than when you started, and you're staring at a decision nobody prepared you for. Do you lock in now before they climb further? Or do you wait and hope they come back down?