Most mortgages qualify you based on your own income. Pay stubs, tax returns, a debt-to-income ratio calculated against your personal finances. That works fine for a primary residence. It works a lot less well when you're buying a rental property and your personal income has nothing to do with whether the deal actually makes sense.
If you're trying to buy your first home in Boston, there's a program that can put up to $50,000 toward your purchase — and a surprising number of eligible buyers have never heard of it. It's the City of Boston's First-Time Homebuyer Program, and unlike a loan, the assistance comes as a grant. As an approved participating lender for the program, I help buyers use it, and I want to walk you through exactly how it works and whether you qualify. What the Program Actually Offers The City of Boston provides income-eligible first-time buyers with a grant toward their down payment. The amount depends on your income relative to the Area Median Income (AMI): Under 100% of AMI: a grant of 3% of the purchase price, up to a maximum of $50,000 — plus closing costs, if applicable. Between 101% and 135% of AMI: a grant of 2% of the purchase price, up to a maximum of $35,000. Deed-restricted properties: the grant is 2% of the purchase price regardless of income tier. The key word is grant. This isn't a second loan you pay back on a monthly basis — it's assistance toward getting you into the home. That's what makes this program so valuable, and why it's worth understanding whether you're eligible before you write off homeownership in Boston as out of reach. Who Qualifies To be eligible for the City of Boston First-Time Homebuyer grant, you generally need to meet all of the following: Be a first-time homebuyer — which the city defines as not having owned a home at any point in the last three years. So if you owned previously but have been renting for three-plus years, you may still qualify. Buy within the city of Boston — the property has to be inside Boston's city limits. Buy an eligible property type — a one- to three-family home or an agency-approved condominium. For a multi-family, one unit must be vacant so you can move in. Live there — the home must be your primary residence. Meet the income limits — household income under 135% of AMI, with the larger grant reserved for those under 100% of AMI. Meet the asset limit — total household assets must be at or below $100,000. This includes checking, savings, stocks, and bonds, but generally does not count most retirement accounts (401k, IRA, and similar) or college savings. The program is need-based, so buyers above that asset level may be deemed ineligible. Complete the required homebuyer education — you'll need to finish a CHAPA-approved Homebuying 101 class, and register for the follow-up HO201 course within 90 days of your purchase. Have a qualifying loan — the program is for a 30-year purchase mortgage (up to 97% loan-to-value). It's not available for refinances, and certain loan types aren't eligible. You also can't receive cash back at closing. Put in a small amount of your own funds — you'll need a minimum contribution from your own money: 1.5% of the purchase price on a one- or two-family home or condo, or 3% on a three-family. The grant helps cover the rest of your down payment and closing costs. Use a participating lender — you must get your first mortgage pre-approval from one of the program's approved lenders, and the loan has to meet Fannie Mae general loan limits. That last point is where I come in — I'm an approved participating lender for this program, so I can get you pre-approved in a way that keeps you eligible for the grant. Which Boston Neighborhoods Are Eligible? The home has to be within Boston city limits, which covers a wide range of neighborhoods — many of them exactly where first-time buyers are looking. Eligible areas include: Dorchester, Roslindale, Hyde Park, Mattapan, West Roxbury, Jamaica Plain, Roxbury, East Boston, South Boston, Charlestown, Allston/Brighton, Fenway/Kenmore, the South End, Back Bay/Beacon Hill, and the Central neighborhoods. That's a lot of Boston — and it includes many of the more attainable neighborhoods where a first-time buyer with grant assistance can realistically compete. If you've been assuming Boston itself is out of reach, the combination of an eligible neighborhood and up to $50,000 in grant money can change that math considerably. Wondering if you qualify for up to $50,000? The eligibility rules have a few moving parts — income, assets, property type. Let's spend fifteen minutes figuring out whether this grant could work for your purchase. As a participating lender, I can walk you through the whole thing. Book a free 15-minute call → How Area Median Income Works (In Plain Terms) The income limits are tied to Area Median Income, which sounds complicated but is straightforward once you see it. AMI is the midpoint income for the Boston area, adjusted for your household size. The city uses percentages of that figure to set who qualifies and for how much. Because AMI depends on your household size and gets updated periodically, the exact dollar cutoffs change. Rather than guess at a number that might be stale by the time you read this, the practical move is to have someone check your specific household against the current limits — which takes about two minutes. The headline to remember: this program is aimed at everyday working buyers, and the income ceiling (135% of AMI) is high enough that a lot of middle-income Boston households qualify. Don't assume you earn too much until you've actually checked. The Steps to Actually Get It Here's the order of operations, because doing these in the wrong sequence can cost you eligibility: Complete the Homebuying 101 class through the Boston Home Center. This is required for any of the city's assistance programs, so start it early. Get pre-approved with a participating lender (like me). Your loan needs to meet the program's requirements, so this step matters before you shop. Find an eligible home in Boston — a one- to three-family or condo that will be your primary residence. Apply for the grant through the Boston Home Center. The full program details and application live on the city's site at boston.gov. But the fastest way to know if this is realistic for you is a quick conversation — I can tell you early whether you're likely to qualify before you invest time in the class and the paperwork. Can You Combine It With Other Programs? Yes — and this is where the real buying power comes in. The City of Boston grant can often be layered with other assistance, most notably MassHousing's down payment assistance program, which offers additional funds. Stacking programs is exactly how buyers who thought they'd never afford Boston end up closing on a home there. That said, combining programs has rules — income qualification has to line up across each program, and some assistance limits things like seller concessions. This is precisely the kind of coordination a participating lender handles, and getting it right is the difference between a smooth close and a stalled one. If you want to understand what a Boston purchase could really look like with assistance stacked, that's a conversation worth having. Frequently Asked Questions Is the City of Boston First-Time Homebuyer grant paid back? The grant portion is a true grant — it's forgiven, with no repayment and no monthly payment. It's assistance toward getting you into the home, not a loan you carry. As always, confirm the specific terms for your situation with a participating lender or the Boston Home Center, since programs can have conditions. How much money can I get? Up to $50,000 (3% of the purchase price) if your household income is under 100% of AMI, or up to $35,000 (2%) if you're between 101% and 135% of AMI. Deed-restricted properties are 2% regardless of income. Do I have to be a first-time buyer? You need to not have owned a home in the last three years. So a previous owner who has been renting for at least three years can still count as a first-time buyer under the program's definition. What kind of home can I buy with it? A one- to three-family home or a condominium, located within the city of Boston, that will be your primary residence. Can I combine it with MassHousing down payment assistance? Often yes — the Boston grant can be layered with MassHousing's DPA and potentially other programs. The exact combination depends on your income and the property, which a participating lender can help you coordinate. Do I have to use a specific lender? Yes. You must get your first mortgage pre-approval from one of the program's approved participating lenders. I'm one of them, so I can keep you eligible while getting you pre-approved. The Bottom Line Boston is an expensive place to buy your first home — but this grant exists specifically to close that gap for working buyers, and it's genuinely underused simply because people don't know about it. Up to $50,000 toward your purchase, as a grant, for a one- to three-family or condo in the city, is the kind of help that turns "someday" into "this year" for a lot of first-time buyers. The eligibility rules have a few moving parts, and the order you do things in matters. As an approved participating lender, I can tell you quickly whether this is realistic for you and help you line it up with any other assistance you qualify for. If you're thinking about buying your first home in Boston, this is absolutely worth a conversation before you rule anything out. For more on buying in and around the city, see our guides to the most affordable cities in Massachusetts, what $500K actually buys in Massachusetts, and how to choose between an FHA and conventional loan. Buying your first home in Boston? Let's find out if you qualify for up to $50,000 through the City of Boston grant — and whether you can stack it with other assistance. I'm a participating lender, and it's a free, no-pressure conversation. Book a free call → | Get a free rate quote → Nate Moghadam is a mortgage loan officer at Fairway Independent Mortgage Corporation and an approved participating lender for the City of Boston First-Time Homebuyer Program. Licensed in Massachusetts and 13 other states. NMLS #906770 | Company NMLS #2289. This content is for informational purposes only and does not constitute a commitment to lend. Program terms, grant amounts, income and asset limits, and eligibility requirements are set by the City of Boston, are subject to change, and are determined by the program administrator — not by Fairway. Figures cited reflect program information available at the time of writing; confirm current details with the Boston Home Center. All loans subject to credit and property approval. Equal Housing Opportunity. Legal Disclosures.
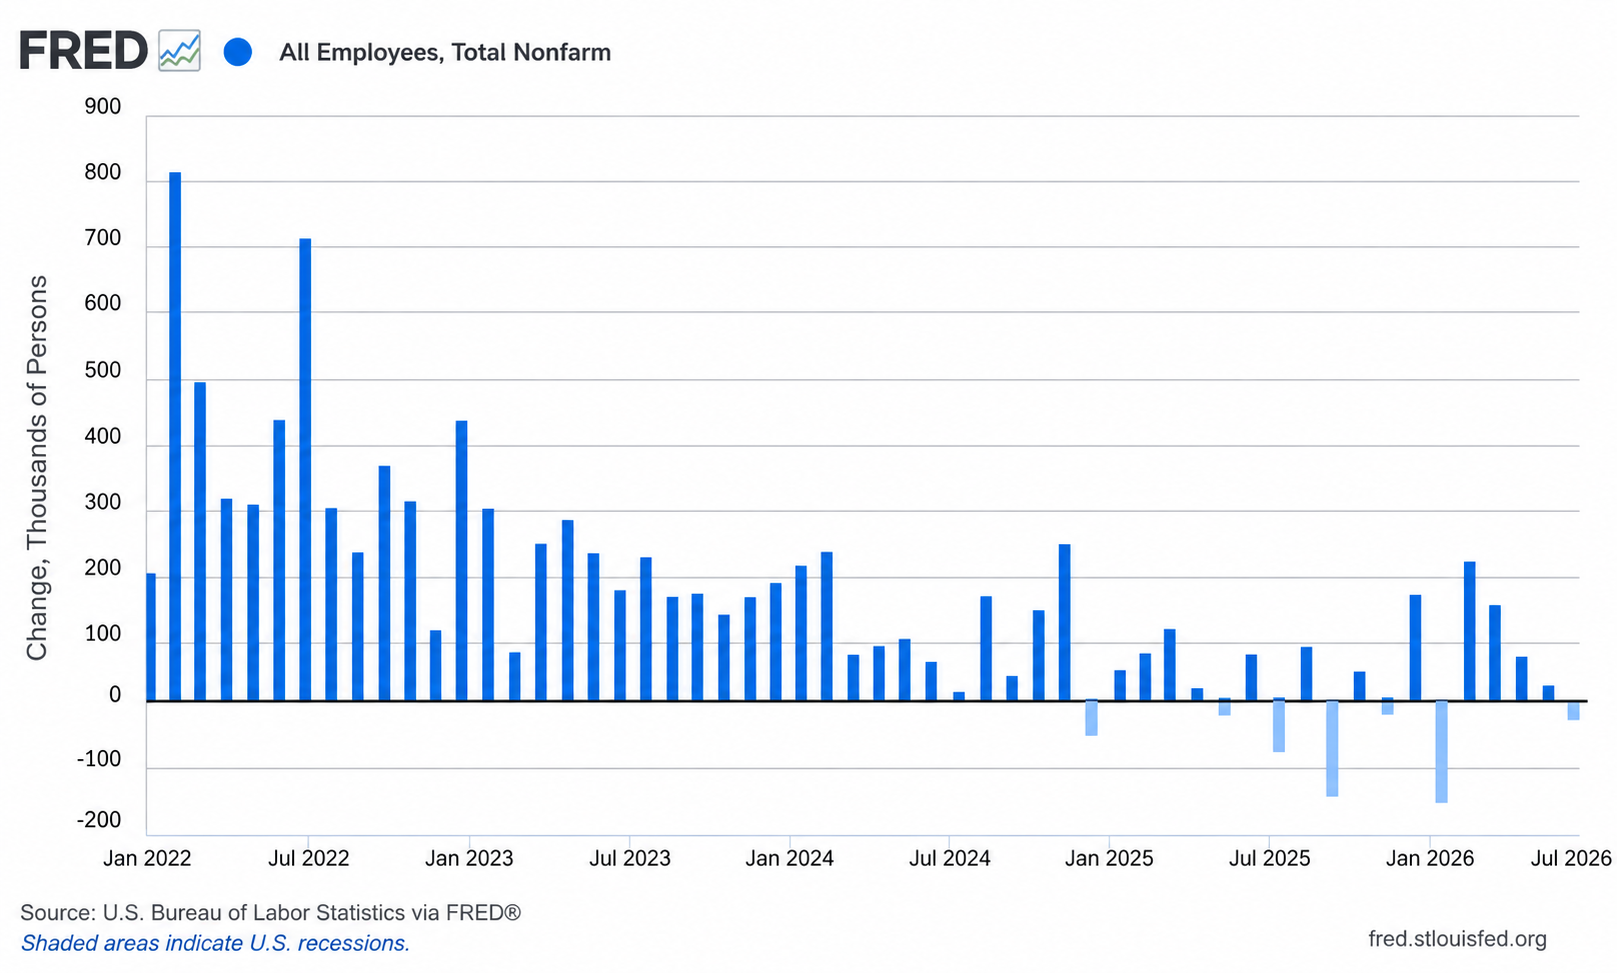
This morning brought a genuine surprise — and for anyone watching mortgage rates, it moved things in the direction buyers have been hoping for. Here's what happened with July's jobs report, in plain English, and what it actually means for your rate. The Headline: The Economy Lost Jobs The July jobs report showed the U.S. economy lost 23,000 jobs last month. That's not a small miss — forecasters had expected a gain of around 83,000. Instead of adding jobs, the economy shed them, which is the kind of number that gets the market's attention fast. There was a second data point that looked good on the surface but wasn't: the unemployment rate actually ticked down to 4.1%. Normally that's positive news. This time it wasn't, because unemployment fell for the wrong reason — people left the workforce rather than found jobs. Labor force participation dropped to 61.4%, its lowest level in more than five years. When people stop looking for work, they're no longer counted as unemployed, which can make the headline rate look better even as the underlying picture weakens. Why Mortgage Rates Eased Here's the part that matters for your wallet. When the economy shows weakness, investors tend to move money into the safety of bonds. That pushes bond prices up and bond yields down — and mortgage rates track the 10-year Treasury yield closely. That's exactly what happened. After the report, the 10-year Treasury yield fell to around 4.62%, and shorter-term yields dropped even more sharply. Mortgage rates followed. Just earlier this week, the average 30-year fixed had been climbing toward 7%. After the jobs news, it eased back into the mid-6% range. So unlike the last few weeks — when a hawkish Fed was pushing rates up — this report nudged them back down. It's a meaningful shift in tone, even if it's only one report. Wondering if this is your window? Rates move daily, and nobody can promise where they go next — but I can help you understand your real options right now, including a free float-down if rates drop after you lock. Let's run your numbers. Book a free 15-minute call → What It Means for the Fed This report lands the Federal Reserve in a genuinely difficult spot. Just a couple of weeks ago, at their last meeting, several Fed members were actually pushing to raise rates to fight stubborn inflation — the most hawkish tone in years. Now, a jobs contraction complicates that entirely. After the report, traders quickly cut the odds of a rate hike at the Fed's September meeting to around 44%. In other words, the market rapidly repriced from "the Fed might hike" toward "the Fed probably holds, and might eventually need to cut." But — and this is the honest part — the Fed is boxed in. Inflation is still elevated and sticky, sitting above their 2% target. A weakening job market argues for lower rates. Stubborn inflation argues against it. The Fed can't fully satisfy both at once, which is why policymakers are openly divided. There's no clean signal here, and one month of data doesn't settle it. What This Means If You're Buying or Refinancing Let me give you the straight version, without the hype you'll see elsewhere. This is a real easing, but not a green light to "wait for more." Rates came off their recent highs, which is genuinely good news if you've been watching them creep toward 7%. But one soft jobs report doesn't guarantee a trend, and the sticky-inflation problem hasn't gone away. Anyone telling you rates are definitely about to tumble is guessing — the Fed itself won't make that call. Trying to time the exact bottom is how people miss good windows entirely. If softer rates were your holdup, this is worth a real look. For a buyer who was on the fence specifically because of rates, this easing is exactly the kind of moment worth running your actual numbers — what you'd qualify for, what the payment looks like now versus a few weeks ago, whether it changes your comfortable price range. You can lock and still benefit if rates fall further. This is where a free float-down matters: if you lock in now and rates drop before you close, you can capture the lower rate. That takes some of the "what if I lock at the wrong time" anxiety off the table, which is especially useful in a choppy, headline-driven market like this one. The house still matters more than the rate. The reframe I always come back to: you marry the house and date the rate. If the right home comes along and the numbers work, a slightly-better-or-worse rate shouldn't be the thing that decides it — you can refinance later if rates keep falling. Rates will keep moving; the right house won't wait. The Bottom Line July's job losses surprised the market, pushed bond yields down, and eased mortgage rates off their recent highs — a welcome shift after weeks of upward pressure. But with inflation still sticky and the Fed divided, this is a loosening of pressure, not a clear path to sharply lower rates. For buyers, the smart move isn't to chase a forecast. It's to know your real numbers, understand your options, and be ready to move when the right home and a workable rate line up. If you'd like help figuring out what today's market means for your specific plans, that's exactly what I'm here for. Want to know what today's rates mean for your budget? Let's run your real numbers — what you'd qualify for, your payment, and how to protect yourself if rates keep moving. Free, no pressure. Book a free call → | Get a free rate quote → Nate Moghadam is a mortgage loan officer at Fairway Independent Mortgage Corporation, licensed in Massachusetts and 13 other states. NMLS #906770 | Company NMLS #2289. This content is for informational purposes only and does not constitute financial advice or a commitment to lend. Interest rates and market conditions are subject to change without notice. Rate figures cited reflect approximate national averages on the date of writing and are not a quote or offer of credit; your rate depends on your individual circumstances. All loans subject to credit and property approval. Equal Housing Opportunity. Legal Disclosures.
New Hampshire has a reputation as the affordable New England alternative — no income tax, no sales tax, and lower home prices than Massachusetts. Relative to its neighbor, that reputation holds up. But "affordable" is carrying a lot of weight in that sentence, because the statewide median single-family home price climbed past $530,000 in early 2026.
If you're self-employed, you already know the frustration. You have a good business, money in the bank, and a strong credit score — but every time you talk to a lender, they look at your tax returns, see a small net income after all your write-offs, and tell you that you don't qualify for the loan you know you can afford.
The Federal Reserve met this week, and if you're waiting for mortgage rates to fall before you buy or refinance, the news wasn't what you were hoping for. Here's what happened, in plain English, and what it actually means for your rate. What the Fed Did The Fed left its benchmark rate unchanged at a range of 3.5% to 3.75% — the move most people expected. But the headline isn't the hold. It's the split: three members of the committee voted to raise rates, the most dissents in favor of a hike since 2016. That direction matters. For most of the past year, the debate was about when the Fed would cut. This meeting flipped that script — the pressure inside the room right now is toward hiking, not cutting, because inflation is still running above the Fed's 2% target and a few officials want to act on it. Fed Chairman Kevin Warsh said the committee "will not hesitate to act" to bring inflation down, and pointedly declined to give any forward guidance about where rates go next. Why Mortgage Rates Actually Went Up Here's the part that trips people up every time: the Fed holding its rate steady did not keep mortgage rates steady. In fact, mortgage rates rose after the meeting. That's because mortgage rates don't track the Fed's benchmark rate directly. They track the bond market — specifically the 10-year Treasury yield. And after the Fed's hawkish tone and those three dissents, bond yields jumped: the 10-year climbed toward 4.7%, and the 30-year Treasury topped 5.2%, its highest level since 2007. When Treasury yields rise, mortgage rates follow. The average 30-year fixed is now hovering in the high-6% range, near a one-year high. So the takeaway isn't "the Fed held, so my rate is safe." It's the opposite: the market read the Fed as more willing to fight inflation, and rates ticked up in response. Trying to time your rate? I can't predict the market — nobody can — but I can help you understand your real options right now, including a free float-down if rates drop after you lock. Let's talk through your numbers. Book a free 15-minute call → The Inflation Report: Good News With an Asterisk The day after the Fed meeting, we got the June reading of the PCE index — the Fed's preferred inflation gauge. And on the surface, it was encouraging: headline inflation cooled to 3.7% year over year (down from 4.1%), and core inflation eased to 3.3%. But here's the asterisk, and it's a big one. That cooldown was driven almost entirely by falling gas prices — energy goods dropped 9.2% in June, the biggest monthly decline since 2022, during a brief ceasefire in the Middle East conflict. That ceasefire has since broken. Gas is back above $4 a gallon, and oil has climbed sharply in the second half of the month. In other words, the one genuinely good inflation number we got is already stale. Nearly every analyst reading it said the same thing: the June cooldown is likely a temporary blip, and inflation may well tick back up in the July and August reports as energy prices reverse. The Fed knows this too — which is exactly why three members are pushing to hike. What This Means If You're Buying or Refinancing Let me be straight with you, because this is where a lot of buyers make a costly mistake. Waiting for rates to drop is a weak bet right now. The Fed's next move might be a hike, not a cut. The one good inflation number is already undone by rising oil. And the market is pricing in more inflation risk, not less. Nobody can promise where rates go, but the current momentum is not in the "rates are about to fall" direction. If your plan is to sit on the sidelines until rates come down, you may be waiting a long time — and paying rising home prices while you wait. The house matters more than the rate. Here's the reframe I give clients: you marry the house, you date the rate. If you find the right home and the numbers work at today's rate, waiting for a hypothetical better rate can cost you the house — and you can always refinance later if rates fall. Meanwhile, if rates rise further, buying now looks smart in hindsight. There are ways to manage the rate risk. Rate buydowns, seller concessions to cover points, and adjustable-rate options all exist for a reason. And a free rate float-down means if you lock now and rates drop before closing, you can still capture the lower rate. The right move depends entirely on your situation — which is exactly the kind of thing worth talking through with someone before you decide. The Bottom Line The Fed held rates, but the tone turned hawkish, mortgage rates rose, and the one encouraging inflation number is already being reversed by rising oil prices. For anyone waiting on the sidelines for a big rate drop, the honest read is: don't count on it happening soon. That doesn't mean rush into a bad decision. It means make your decision based on the home, your budget, and the real numbers in front of you — not a rate forecast that even the Fed won't make. If you want help figuring out what today's market means for your specific plans, that's what I'm here for. Wondering what today's rates mean for your budget? Let's run your real numbers — what you'd qualify for, what your payment looks like, and how to protect yourself if rates move. Free, no pressure. Book a free call → | Get a free rate quote → Nate Moghadam is a mortgage loan officer at Fairway Independent Mortgage Corporation, licensed in Massachusetts and 13 other states. NMLS #906770 | Company NMLS #2289. This content is for informational purposes only and does not constitute financial advice or a commitment to lend. Interest rates and market conditions are subject to change without notice. Rate figures cited reflect national averages on the date of writing and are not a quote or offer of credit; your rate depends on your individual circumstances. All loans subject to credit and property approval. Equal Housing Opportunity. Legal Disclosures.
This is hands down one of the most common questions I get: "I already signed the Loan Estimate" — or "I already locked my rate" — "so I'm stuck with this lender now, right?"
You just got pre-approved. A few days later, an email shows up with a PDF attached: your Loan Estimate. Three pages, a wall of numbers, and about ninety seconds before most people's eyes glaze over.
New Hampshire has quietly become one of the hottest housing markets in the country — the Manchester-Nashua metro literally ranked #1 out of 300 U.S. markets recently. So if you're shopping with a $500,000 budget, the real question isn't "can I find something" — it's "where does that number give me options, and where does it barely get me in the door?" The answer changes dramatically from town to town. Let me break down what $500K actually buys across New Hampshire in 2026, and why the exact figure you're working with matters more than you'd think. First, Where $500K Sits in the Market As of 2026, New Hampshire's statewide median home price is hovering right around $500,000 to $525,000, depending on which source you check. That means a $500K budget puts you approximately at the middle of the entire state market. That's an important starting point, because "at the median" means something specific: roughly half the homes in the state are above your budget and half are below. You're not priced out, but you're not shopping the luxury tier either. Where you land — options and leverage versus competing hard — comes down entirely to which town you're looking in. The $450K Trap (And Why $500K Changes Everything) Here's something I tell buyers all the time, and it surprises people. There's a real difference between shopping at $450,000 and shopping at $500,000 in New Hampshire — and it's bigger than the $50,000 gap suggests. At $450K and below, you're competing in the most crowded, most inventory-starved part of the market. New Hampshire's supply is tight — around 1.4 months of inventory in the southern part of the state, which is deep seller's-market territory. In that price range you're up against first-time buyers, investors, and everyone else fighting for the limited stock at the entry level. Bidding wars, waived contingencies, offers over ask — that's the $450K experience right now. Push up to $500K and the dynamic shifts. You clear into a range where more towns become realistic, inventory opens up, and — critically — you gain leverage. You're no longer at the bottom of the stack fighting for scraps; you're a serious buyer with real options, which means more room to negotiate, more time to think, and less pressure to overpay just to win. That extra $50K doesn't just buy more house — it buys you a better position. Not sure what your real budget is? The difference between qualifying for $450K and $500K often comes down to small things — debts, down payment, how your income is documented. Let's find your actual number so you know which market you're really shopping in. Book a free 15-minute call → What $500K Buys, Town by Town Southern New Hampshire — where most of the jobs, the commuter access, and the demand are concentrated — varies wildly by town. Here's the lay of the land: Manchester (median ~$446K): The state's largest city, and at $500K you're shopping above the median here — which means genuine options and leverage. You can realistically land a solid single-family home in good condition. Manchester is the sweet spot for a $500K budget: your money clears the median with room to spare, so you're negotiating from strength rather than stretching. Concord (median ~$410K): The state capital offers real value, and $500K goes a long way — you're well above median, opening up larger or nicer homes. The tradeoff is that Concord homes move fast (often under contract in about ten days), so being fully pre-approved and ready to move matters. Merrimack (median ~$495K): Right in the middle, and $500K puts you at market. A popular commuter town between Manchester and Nashua — expect to be competitive but not priced out. Nashua (median ~$514K): One of the fastest-appreciating markets in the state, up double digits year over year. At $500K you're just under the median here, which means you're competing harder and may be looking at homes needing some work, or smaller footprints. Still very doable, but Nashua is where a $500K budget starts to feel stretched rather than comfortable. Bedford (median ~$1.195M): Reality check — Bedford's premium schools and location put it well out of reach at $500K. Worth knowing so you don't fall in love with a town your budget doesn't match. Don't Forget the Property Tax — It Changes Your Real Budget This is the piece New Hampshire buyers most often underestimate, and it directly affects both your monthly payment and how much home you qualify for. New Hampshire has no income tax and no sales tax — which sounds great until you see how the state makes up the difference: property taxes among the highest in the country, averaging roughly 2% of a home's value per year. On a $500,000 home, that's around $10,000 annually, or about $830 a month — just in property tax. That number gets folded into your monthly mortgage payment through escrow, and it counts against the debt-to-income ratio lenders use to qualify you. So two buyers with identical incomes and identical $500K target prices can qualify for different loan amounts depending on the property tax rate of the specific town. A higher-tax town effectively shrinks your buying power. When you're comparing homes, the tax line matters as much as the sticker price — sometimes more. If you're weighing a move from Massachusetts, this is doubly important, and I wrote a full breakdown of the cross-border tax math here: living in New Hampshire, working in Massachusetts — the tax math nobody explains before you buy. What the Monthly Payment Actually Looks Like Let's put real numbers on a $500,000 home in New Hampshire, with 5% down at a rate around 6.5%: Principal & interest: roughly $3,000/month on a ~$475K loan Property taxes: roughly $830/month (at NH's ~2% average) Homeowners insurance: roughly $150/month PMI (because you're under 20% down): roughly $150–200/month That lands you around $4,100–$4,200 a month all in. Notice how much of that is property tax — in a lower-tax state the same home would cost meaningfully less per month. This is exactly why the "what can I afford" conversation has to happen before you start touring homes, not after you've fallen for one. For a sense of the income behind that payment, see how much you need to earn to buy at different price points — the framework applies on both sides of the border. The Bottom Line At $500K in New Hampshire, you're a median buyer with real options — but where those options are best depends heavily on the town. Manchester and Concord give you leverage and room; Merrimack keeps you competitive; Nashua stretches you; Bedford is out of reach. And across all of them, the property tax line quietly shapes what you can actually afford month to month. The smartest move is to get your real, precise budget nailed down first — including the property tax of your target towns — so you're shopping in the range where you have leverage instead of the one where you're fighting uphill. That's where I come in. Shopping for a home in New Hampshire? I'm licensed in New Hampshire and Massachusetts, and I'll help you pin down your real budget — factoring in each town's property tax — so you know exactly where you have leverage. Let's talk before you start touring. Book a free call → | Start my pre-approval → Nate Moghadam is a mortgage loan officer at Fairway Independent Mortgage Corporation, licensed in New Hampshire, Massachusetts, and 12 other states. NMLS #906770 | Company NMLS #2289. This content is for informational purposes only and does not constitute a commitment to lend. Home prices, property tax rates, mortgage rates, and payment estimates are approximate, vary by municipality and individual circumstances, and are subject to change. Payment examples are illustrative and not an offer of credit. All loans subject to credit and property approval. Equal Housing Opportunity. Legal Disclosures.
Here's a scenario I run into all the time: someone working in Massachusetts is eyeing a move across the border to New Hampshire. The pitch sells itself — "New Hampshire has no income tax." Live free or die, keep more of your paycheck, buy more house.